Finding a personal loan in Tennessee depends on what you actually need. Are you looking for a quick cash injection for an emergency, or do you need a structured loan to consolidate debt? Your credit score is the first thing you should check, since it determines whether you’ll qualify for low-interest bank rates or those high-speed cash advances.
Sorting Through the Local Lending Landscape
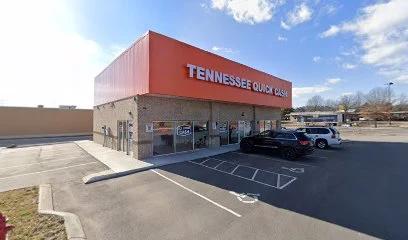
There’s a massive variety of lenders in Tennessee, and the “best” one depends on your situation. If your HVAC unit dies in the middle of a July heatwave, you probably don’t care about a 60-month term; you just want cash today. In those cases, specialized providers like Tennessee Quick Cash offer small amounts starting as low as $10 up to $4,000, and they let you visit a physical location if you’d rather not deal with a smartphone app.
If you’re planning a wedding or a major home renovation, a different approach makes more sense. Traditional banks and credit unions offer much more breathing room for larger, planned expenses. You get more stability here, but you have to play by their rules regarding credit history and documentation.
It helps to categorize these lenders by their purpose. Some are built for speed, while others focus on affordability. If you try to use a high-speed cash advance service to pay off a mortgage, you’ll end up in a hole. Conversely, trying to use a major bank to cover a $50 emergency might take too long. Knowing which tool to use for the job is half the battle.
A lot of people get caught in the middle by applying for everything at once. They see an ad for an instant loan and hit “apply” on five different websites. This can actually hurt your credit score through multiple hard inquiries. It’s better to walk into a branch or use a single comparison tool like Loans TN to see what your options look like before you commit.
Comparing Interest Rates and Loan Amounts
The math behind these loans gets messy quickly. You have to look past the monthly payment and look at the APR. A low monthly payment often means you’re paying for a much longer term, which makes the total cost of the loan much higher. For example, a $5,000 loan over 12 months is cheap; the same loan over 60 months will cost you thousands more in interest.
Credit unions often provide the most competitive rates in the state. For instance, Leaders Credit Union offers rates that can go as low as 3.99% APR, which is much lower than what most big-box banks or online lenders offer. They also provide long terms, sometimes stretching up to 96 months, which helps keep your monthly obligations manageable.
If you aren’t looking for a massive lump sum, some lenders focus on smaller, more accessible credit lines. You might just need a few hundred dollars to bridge the gap until your next paycheck. Here is a quick breakdown of how different Tennessee lenders structure their offerings:
| Lender Type | Typical Loan Amounts | Best For | Speed of Funding |
| Cash Advance Services | $10, $4,000 | Immediate emergencies | Very Fast (Same Day) |
| Credit Unions | Varies (usually higher) | Debt consolidation / Large purchases | Moderate (Days) |
| Traditional Banks | Varies | Planned expenses / Home improvement | Slowest (Several days) |
| Lines of Credit | $200, $3,000 | Ongoing small expenses | Fast (Online/In-store) |
Don’t ignore local branches if you have questions. Many people think everything has to be done via an app, but sometimes talking to a human at a desk is the only way to clear up a confusing requirement. If you’re unsure about the fine print, a quick phone call can save you a lot of headache later.
Deciding Between an Online App or a Local Branch
Technology has changed how we borrow money, but it hasn’t made it any less complicated. Online lenders are great because you can apply at 2:00 AM from your couch. You can get a decision in minutes, and for many, the funds are available almost instantly. This is why many people search for “instant” loans, though you must be careful about the interest rates attached to that speed.
But there is real value in walking into a physical building. At Tennessee State Bank, for example, you can actually sit down with a representative. If your income is irregular, maybe you work in construction or you’re a freelancer, a computer algorithm might reject you automatically. A human loan officer can look at your actual life situation and might find a way to make the loan work that an app would miss.
I remember a friend who was trying to get a small loan to fix his truck so he could get to work. He applied for an online loan and got rejected because his pay stubs looked “unconventional” to the software. He went to a local branch the next morning, showed his bank statements, and got approved in an hour. It wasn’t about the money; it was about being able to prove his ability to pay back what he borrowed.
When choosing between the two, consider these factors:
- Accessibility: Do you have the documents ready to upload online right now?
- Relationship: Do you already have a checking account at a local Tennessee bank?
- Complexity: Is your financial situation straightforward or “messy”?
- Urgency: Do you need the money this afternoon or next Tuesday?
Understanding the Real Cost of Debt Consolidation
A major reason people look for personal loans in Tennessee is to consolidate debt. If you have three different credit cards with 25% interest rates, taking out one personal loan at 12% interest makes sense. You’re essentially paying for the privilege of having only one bill to worry about each month, and you’re paying less to the bank in the process.
However, consolidation only works if you actually stop using the credit cards once they are paid off. If you clear your balances with a loan and then immediately run the credit cards back up to their limits, you’ve just doubled your debt. This is a trap that many people fall into when they feel the temporary relief of a zeroed-out credit card balance.
You should also look at Tennessee Valley Federal Credit Union or similar institutions that offer specific terms for debt consolidation. They often provide more competitive rates because they know you’re trying to be responsible. They want to see that you’re moving from high-interest “bad” debt to lower-interest “good” debt. It’s a way for the credit union to help you, and a way for them to ensure they get paid back steadily.
If you’re looking at a large amount, like $30,000, you need to run the math on your monthly payment. A $30,000 loan at a decent interest rate over five years can be a significant monthly commitment. It’s not just about whether you can afford the payment today; it’s about whether you can afford it if your hours get cut or your car breaks down next month. Always build a small buffer into your budget before signing on the dotted line.
The Truth About “Easy” Loans and Hidden Fees
People often ask which lender is easiest to get a loan from. The truth is, the “easiest” lenders are often the most expensive. If a lender tells you that anyone can get a loan regardless of credit history, they’re likely going to charge you an interest rate that feels like a penalty. These are the lenders you use for a $200 emergency to get you through the week, not for long-term financial planning.
You need to look for “hidden” costs that don’t show up in the headline interest rate. Some lenders charge an origination fee, which is a percentage of the loan taken off the top. If you borrow $1,000 but they take a $100 origination fee, you only get $900, but you’re still paying interest on the full $1,000. Always ask: “What is the total amount I will have paid back by the time this is finished?”
Another thing to watch for is the prepayment penalty. Some lenders make their money by charging you a fee if you try to pay the loan off early. If you come into extra money from a tax refund or a bonus, you want to be able to kill that debt immediately without being penalized for being responsible. Always check the contract for clauses regarding “prepayment” or “early termination.”
But let’s address the skepticism: “Is it really worth the hassle of a bank loan if an app is faster?” If you’re borrowing more than $1,000, the answer is usually yes. The difference between a 29% interest rate from a quick app and a 9% rate from a local credit union can be thousands of dollars over the life of the loan. Speed is a luxury that costs money; if you can afford to wait a few days, you should always choose the cheaper option.
Quick answers
Where can I get an online loan in Tennessee?
You can apply through various online lenders and credit unions that specialize in Tennessee personal loans, providing digital access to funds without visiting a physical branch.
Which lender is easiest to get a personal loan from?
Lenders with lenient credit requirements, such as online installment loan providers or bad credit specialists, are generally the easiest to qualify with.
How much would a $30,000 personal loan cost a month?
A $30,000 loan typically costs between $600 and $900 per month, depending on your interest rate and the repayment term length.
Which loan app gives $20,000 instantly?
Most loan apps offer smaller amounts for instant funding, while $20,000 typically requires a standard application process that takes a few business days to finalize.
What are the requirements for a personal loan in Tennessee?
Applicants generally need to be at least 18 years old, a resident of Tennessee, and have a steady source of income to prove repayment ability.

